Paying for college in the United States can look overwhelming when you see a published annual cost of tens of thousands of dollars. But the published price is only the beginning of the financial conversation. The more useful question is not:
“How can I find a scholarship?”
It is:
“How can I build a realistic funding plan that reduces my actual college cost and keeps the remaining amount manageable?”
That difference matters because financial aid is not one single type of money. A student’s funding package may contain grants, scholarships, work-study, loans, institutional aid, or other resources. Some reduce the amount you owe without repayment, some require you to work, and some create debt.
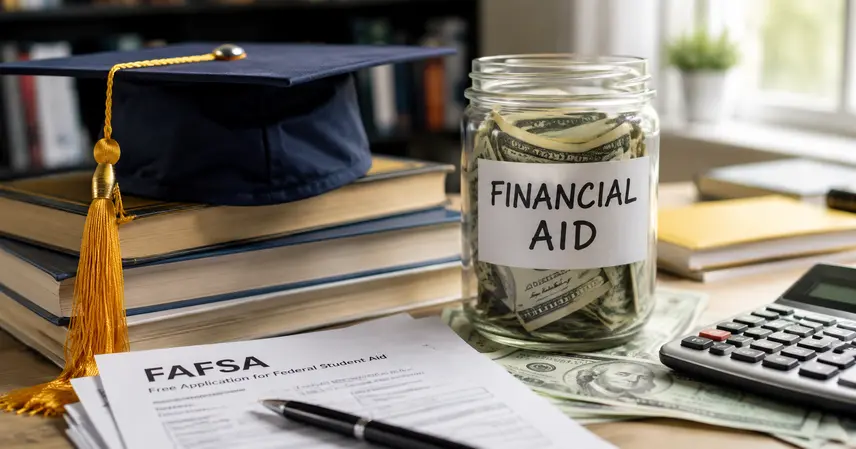
Federal Student Aid explains that FAFSA information can be used for federal grants, Federal Work-Study, and federal student loans, while states, colleges, and some private aid providers may also use FAFSA information when determining eligibility.
For international students, the strategy is different again. Federal student aid is generally not the main route, so institutional scholarships and college-specific financial aid policies become much more important. EducationUSA recommends beginning financial planning early and evaluating both educational and living costs when researching U.S. study options.
This guide shows you how to approach financial aid as a decision-making problem, not simply a scholarship search.
Before Looking for Aid, Calculate Your Funding Gap
The first mistake many students make is searching for financial aid before knowing how much money they actually need. Start with four numbers:
1. Total Cost of Attendance
This can include tuition, fees, housing, food, books, transportation, insurance, and other estimated educational expenses.
2. Grants and Scholarships
These are the forms of assistance that generally reduce the amount you need to finance without creating ordinary loan debt.
3. Realistic Family Contribution
This is what your family can actually contribute—not what you hope they can contribute and not necessarily what a college’s estimate assumes.
4. Remaining Funding Gap
Use this simple framework:
Funding Gap = Total Cost − Grants − Scholarships − Realistic Family Contribution
Suppose a college’s estimated annual cost is: $65,000
You receive: $22,000 in grants and scholarships
Your family can realistically contribute: $25,000
Your remaining gap is: $18,000
That $18,000 is the number you need to solve.
This is much more useful than saying:
“I received $22,000 in financial aid.”
Why?
Because the purpose of financial aid is not to produce an impressive-looking award letter. The purpose is to make the remaining cost manageable.
The Most Important Distinction: Aid Is Not All Equal
When students hear “financial aid,” they sometimes treat every dollar as equivalent. It isn’t. Consider four broad categories:
| Funding Type | How It Helps | Repayment/Work |
|---|---|---|
| Grant | Reduces education cost | Generally not repaid if conditions are met |
| Scholarship | Reduces education cost | Generally not repaid if conditions are met |
| Work-Study | Helps you earn money through employment | Requires work |
| Loan | Provides borrowed funds | Must generally be repaid |
Federal Student Aid describes Federal Work-Study as part-time employment through which eligible students earn money to help pay education expenses. It is therefore fundamentally different from a grant that is awarded without requiring employment. This leads to a useful way to rank funding:
Grant/scholarship → earned income → borrowing
That is not a universal rule for every student’s circumstances, but it is a useful framework when evaluating how financially burdensome each source may be.
1. Complete the FAFSA if You Are Eligible
For eligible students, the FAFSA is one of the central starting points for U.S. financial aid. The FAFSA is free to submit. Federal Student Aid says it can provide access to federal grants, Federal Work-Study, and federal student loans, and that states, schools, and some private aid providers may also use FAFSA information to determine eligibility for their programs.
Why You Should Not Guess Your Eligibility
A student may think:
“My family probably earns too much, so there is no reason to apply.”
That assumption can be risky. Different programs have different eligibility requirements, and FAFSA information can be used beyond federal student aid. The practical approach is simple:
Do not reject yourself before the official process does.
Check the current requirements and deadlines for your situation.
Review Your FAFSA Information
After submitting FAFSA, do not simply forget about it. Federal Student Aid explains that the FAFSA Submission Summary contains information about your application and an Eligibility Overview, including estimated federal aid and your Student Aid Index (SAI). The estimated aid shown there is not the same as a final financial-aid offer from your college. That distinction is important. FAFSA result ≠ final college financial-aid offer. The college ultimately determines the aid it offers.
2. Don’t Stop at FAFSA: Check Every College’s Institutional Aid
One of the biggest weaknesses in a basic financial-aid strategy is treating FAFSA as the entire process. It isn’t. Colleges may have their own:
- Grants
- Merit scholarships
- Need-based institutional aid
- Tuition awards
- Departmental scholarships
- Special scholarships
- International student awards
The important question is: What financial assistance does this particular college offer to someone like me?
Do not assume that two colleges with similar tuition prices have similar financial-aid policies. They may have very different approaches to institutional aid.
Build a College Aid Profile
For every college on your list, record:
| Question | Your Answer |
|---|---|
| Total estimated cost | |
| Institutional grants | |
| Merit scholarships | |
| Need-based aid | |
| International aid | |
| FAFSA required? | |
| CSS Profile required? | |
| Separate aid form? | |
| Scholarship deadline | |
| Financial-aid deadline | |
| Renewal requirements |
This simple table can prevent one of the most common financial-aid mistakes: assuming every college uses the same process. They don’t.
3. Use the Net Price Calculator Before Falling in Love With a College
Published tuition is not the same thing as net price. A college may have a high published cost but offer substantial institutional aid to a particular student. Another college may advertise a lower price but provide less assistance. That is why prospective students should investigate the college’s Net Price Calculator when available. The goal is to estimate: What might this college actually cost me after applicable grants and scholarships?
Example
Consider two fictional universities:
| University A | University B | |
|---|---|---|
| Published annual cost | $48,000 | $68,000 |
| Estimated grants/scholarships | $8,000 | $30,000 |
| Estimated remaining cost | $40,000 | $38,000 |
University B looks much more expensive from its published price. But its estimated remaining cost may actually be lower. This is why a student who chooses colleges based only on advertised tuition can make poor financial decisions.
The Better Question
Don’t ask:
“Which college is cheapest?”
Ask:
“Which college is likely to give me the best combination of academic fit and sustainable net cost?”
EducationUSA similarly advises students to consider academic, financial, and personal fit when researching U.S. institutions rather than treating a single ranking or price as the deciding factor.
4. Check Whether the College Uses the CSS Profile
The FAFSA is not the only financial-aid form students may encounter. The CSS Profile is an online application used by participating colleges and scholarship programs to award non-federal institutional aid. College Board explicitly advises students to check each college to determine whether the CSS Profile is required. This creates an important distinction:
FAFSA → federal aid and other programs that use FAFSA information
CSS Profile → institutional, non-federal aid at participating institutions
A student who completes FAFSA but fails to submit another required institutional aid application could potentially miss an important source of assistance.
Don’t Assume Every College Requires CSS Profile
This is equally important. CSS Profile is not a universal requirement. For every college, check:
- FAFSA requirement
- CSS Profile requirement
- Institutional application
- Scholarship application
- Priority deadline
- Supporting documentation
College Board says CSS Profile deadlines vary by school, so students should verify the deadline for every participating institution.
5. If You Are an International Student, Change Your Strategy
International students should not simply copy the financial-aid strategy of a U.S. domestic applicant. The funding landscape can be substantially different. EducationUSA maintains financial-aid resources specifically for students exploring U.S. study, including scholarships and other opportunities.
Read More: 13 Effective Time Management Tips for College Students to Succeed Academically
The first question for an international applicant should therefore be: Does this college actually provide financial assistance to international students? Then ask:
- Is it need-based?
- Is it merit-based?
- Is it full or partial?
- Is the scholarship automatic?
- Is a separate application required?
- Does the college require CSS Profile?
- What financial documents are required?
- What is the deadline?
- Is the award renewable?
College Board notes that many colleges provide institutional financial aid to international students and that CSS Profile can collect information about an international family’s income, assets, and expenses in the family’s home currency.
A Crucial International-Student Strategy
Do not build your college list first and ask about affordability later. Reverse the process.
Academic fit + financial-aid availability + expected net cost
Should all influence your college list from the beginning. If a college is academically perfect but offers little realistic aid to international students, it may not belong in the same category as a college that offers substantial institutional support.
6. Target Merit Scholarships by Fit, Not Volume
Searching for scholarships can become a full-time activity if you use the wrong strategy. Typing:
“college scholarships”
into a search engine produces an enormous number of possibilities. The problem is not finding scholarships. The problem is finding scholarships for which you are genuinely competitive. Instead, search through your personal profile.
Build Your Scholarship Profile
Write down:
Academic profile
- GPA
- Test scores, where relevant
- Academic achievements
- Advanced coursework
Academic direction
- Intended major
- Career interest
- Professional goals
Activities
- Sports
- Clubs
- Leadership
- Volunteering
- Community involvement
Background
- Location
- School
- Family circumstances
- First-generation status, if applicable
- Other eligibility characteristics
Then combine these categories. For example:
Engineering + undergraduate scholarship
Future teacher + scholarship
Community service + scholarship
First-generation + college scholarship
STEM + high school senior scholarship
This produces a much more focused search.
7. Search Locally Before Chasing Only National Scholarships
National scholarships may have thousands of potential applicants. Local scholarships can have narrower eligibility requirements. Look for opportunities from:
- Community foundations
- Local businesses
- Civic organizations
- Professional associations
- Employers
- School districts
- High school counseling offices
- Local nonprofit organizations
The key advantage is not that local scholarships are automatically easier. It is that eligibility may be more narrowly defined. For example, a scholarship might be limited to:
Students graduating from a particular high school in a particular county who plan to study nursing.
That is much more targeted than a scholarship open to every student in the country.
Ask Your School Directly
A surprisingly effective question is:
“What scholarships have students from this school successfully applied for in previous years?”
Your counselor may know opportunities that are difficult to discover through a generic internet search.
8. Search by Major, Career, Activity, and Identity
Do not limit scholarship research to your intended major. A student’s profile can intersect with several scholarship categories. For example, a future engineering student might search:
- Engineering scholarships
- STEM scholarships
- Women in engineering scholarships, where applicable
- Robotics scholarships
- Community service scholarships
- Local scholarships
- Academic scholarships
A future teacher might search:
- Education scholarships
- Future teacher scholarships
- Community service scholarships
- Local foundation scholarships
- Subject-specific teaching scholarships
This creates a scholarship portfolio, rather than one giant search.
9. Understand Work-Study Before Counting It as Financial Aid
Federal Work-Study can be useful, but students should not treat it like a grant. Federal Student Aid explains that Federal Work-Study provides part-time employment opportunities for eligible students and that jobs are limited. Students generally need to submit FAFSA to be considered. Imagine your financial-aid offer says:
Federal Work-Study: $4,000
It would be a mistake to think:
“The college just gave me $4,000.”
Instead, understand it as:
“I may have an opportunity to earn up to the stated amount through eligible employment under the program.”
Federal Student Aid also notes that work-study jobs are limited and that students may need to find and apply for available positions themselves.
Ask These Questions
Before relying heavily on work-study:
- How many hours would I realistically need to work?
- What jobs are available?
- When are students paid?
- Is the job guaranteed?
- Will working interfere with my coursework?
- Is the expected income enough to close my funding gap?
This turns work-study from a vague line on an aid offer into a realistic income estimate.
10. Compare Financial-Aid Offers Using Net Cost, Not “Total Aid”
This is where many students make their biggest financial mistake. Suppose you receive two offers.
College A
Annual cost: $72,000
Grant: $18,000
Scholarship: $12,000
Work-study: $4,000
Loan: $8,000
College B
Annual cost: $55,000
Grant: $10,000
Scholarship: $8,000
Work-study: $2,000
Loan: $3,000
College A appears to provide more aid.
$42,000 versus $23,000.
But College A still has a much higher starting cost. Now compare the remaining cost after grants and scholarships:
College A
$72,000 − $18,000 − $12,000
= $42,000
College B
$55,000 − $10,000 − $8,000
= $37,000
College B may therefore be the less expensive option even though its financial-aid package looks much smaller. And there is another issue:
The type of aid matters.
A $4,000 work-study award is not equivalent to a $4,000 grant.
An $8,000 loan is not equivalent to an $8,000 scholarship.
This is why the correct comparison is:
Net cost + type of aid + remaining funding gap
not:
Total aid displayed on the offer.
Federal Student Aid specifically notes that estimated aid shown in the FAFSA Submission Summary is not a guaranteed final offer and that the college makes the final decision about the aid it offers.
10 Question Tests for Every Financial-Aid Offer
When you receive an offer, ask:
Question 1: How much do I actually have to pay?
Calculate the remaining cost after grants and scholarships.
Question 2: How much of that amount requires borrowing?
Separate loans from other resources.
Question 3: How much depends on me working?
Identify work-study or other expected income.
Question 4: What happens next year?
Check whether scholarships and grants are renewable and what conditions you must maintain. This fourth question is often overlooked. A scholarship that looks excellent in Year 1 may be less attractive if renewal requires conditions that are difficult for you to maintain.
What If Your Aid Offer Is Not Enough?
Sometimes the numbers simply do not work. That does not necessarily mean you should immediately reject the college. First, determine why the funding gap exists. Possible reasons include:
- Your family’s financial circumstances changed.
- The college’s estimate does not reflect current circumstances.
- Your aid package contains insufficient institutional funding.
- A scholarship was not included.
- You missed an additional application.
- Your actual living costs are higher than the estimate.
- The college is simply not financially affordable for your family.
If your financial circumstances have materially changed, contact the financial-aid office and ask whether the college has an appeal or professional-judgment process. Federal Student Aid provides guidance for situations in which the financial aid offered is not enough and encourages students to contact the financial-aid office about their options.
Write a Useful Appeal
Do not simply write:
“I need more money.”
Instead, explain:
- What changed.
- When it changed.
- Why the change affects your ability to pay.
- What documentation you can provide.
- What assistance you are asking the college to reconsider.
A clear financial explanation gives the financial-aid office something concrete to evaluate. There is no guarantee that an appeal will produce additional aid. But an unsupported request is much weaker than a documented explanation of changed circumstances.
Build a Funding Stack Instead of Searching for One Perfect Scholarship
A realistic college funding plan often combines several sources. For example:
Institutional grant
+$18,000
Merit scholarship
+$8,000
External scholarship
+$3,000
Family contribution
+$15,000
Student earnings
+$4,000
Remaining gap
= Amount that still needs to be solved
This is more realistic than expecting one scholarship to solve the entire problem. The goal is to gradually reduce the funding gap.
Think of Financial Aid as Layers
Layer 1: Free money
Grants and scholarships.
Layer 2: Institutional resources
College-specific aid and scholarships.
Layer 3: Earned money
Work-study or other realistic student employment.
Layer 4: Family resources
Savings and an affordable family contribution.
Layer 5: Borrowing
Loans, when necessary and appropriate. This framework helps students understand not only how to get aid, but also how much financial pressure each source creates.
Create a Financial-Aid Calendar
Financial-aid planning becomes much easier when deadlines are visible in one place. Create a spreadsheet like this:
| College | FAFSA | CSS Profile | Institutional Form | Scholarship Deadline | Documents | Status |
|---|---|---|---|---|---|---|
| College A | Oct. 1 | Nov. 15 | Required | Dec. 1 | Pending | |
| College B | Oct. 1 | Not required | Required | Jan. 5 | Complete | |
| College C | Oct. 1 | Dec. 1 | Not required | Feb. 1 | Pending |
The dates above are only examples. Always verify actual deadlines with the institution and current official aid websites. The important point is organizational:
One missed financial-aid deadline can matter more than another ten hours spent searching for scholarships.
Create a Scholarship Application System
Once you identify scholarships, do not manage them through browser tabs and memory. Create a scholarship tracker:
| Scholarship | Amount | Eligibility | Deadline | Essay | Recommendation | Status |
|---|---|---|---|---|---|---|
| A | $2,000 | Local | Oct. 15 | Yes | Yes | Researching |
| B | $5,000 | STEM | Nov. 30 | Yes | No | Drafting |
| C | $1,500 | Community service | Jan. 10 | No | Yes | Ready |
Then prioritize applications using a simple formula:
Eligibility fit + award value + effort required + deadline
A $5,000 scholarship for which you are highly qualified may deserve more attention than a $500 scholarship requiring the same amount of work. This is not about guaranteeing success. It is about allocating your limited application time intelligently.
Don’t Ignore the Renewal Rules
A scholarship is not always a one-time event. Before counting a scholarship as part of your long-term college budget, check:
- Is it renewable?
- For how many years?
- Is a minimum GPA required?
- Must you remain enrolled full-time?
- Must you maintain a particular major?
- Is there a separate renewal application?
- Can the award be reduced if you receive other aid?
This leads to an important concept:
First-year affordability is not the same as four-year affordability.
A college that is affordable in Year 1 but becomes unaffordable in Year 2 may not be a sustainable choice.
Calculate Four-Year Affordability
If you are comparing colleges, do not stop at the first-year price. Create a simplified four-year projection. For example:
| College A | College B | |
|---|---|---|
| Year 1 estimated net cost | $30,000 | $34,000 |
| Year 2 | $32,000 | $33,000 |
| Year 3 | $34,000 | $32,000 |
| Year 4 | $36,000 | $31,000 |
| Estimated 4-year total | $132,000 | $130,000 |
These are hypothetical figures, not predictions. The point is to recognize that the cheapest first year does not necessarily produce the lowest four-year cost. Also investigate whether institutional scholarships are renewable and under what conditions.
Financial Aid Should Influence Your College List
Financial planning should happen before you submit applications, not only after admission. Suppose you have ten potential colleges. You could divide them into:
High financial fit
Colleges where your estimated net cost appears realistically manageable.
Possible financial fit
Colleges where affordability depends on receiving additional aid.
High financial risk
Colleges where you would require a very large funding package to attend. This creates a more useful college list. A college can be academically excellent and still be a poor financial match. That does not mean you should never apply. It means you should understand the risk.
A Practical College Financial-Fit Scorecard
Score each college from 1 to 5:
| Factor | Score |
|---|---|
| Academic fit | /5 |
| Institutional aid potential | /5 |
| Estimated net cost | /5 |
| Scholarship potential | /5 |
| Four-year affordability | /5 |
| Living-cost environment | /5 |
| Funding-gap size | /5 |
Then calculate the overall picture. This is not an official admissions formula. It is a personal decision-making tool. Its purpose is to prevent one emotionally attractive factor—such as prestige—from dominating the financial decision.
A 30 Minute Financial Aid Audit
If the process feels overwhelming, start with this.
Minutes 1–5: List Your Colleges
Write down the schools you are seriously considering.
Minutes 6–10: Record Total Cost
Find the published cost of attendance for each school.
Minutes 11–15: Identify Aid Requirements
Check:
- FAFSA
- CSS Profile
- Institutional forms
- Scholarship applications
Minutes 16–20: Find Institutional Aid
Record the scholarships and grants available to your applicant category.
Minutes 21–25: Calculate the Funding Gap
Estimate:
Cost − Grants − Scholarships − Family Contribution
Minutes 26–30: Identify Your Biggest Gap
Do not immediately search randomly for scholarships.
Ask:
What is the largest unresolved part of my funding plan?
If the gap is $20,000, a $300 scholarship is useful but will not solve the central problem. You may need to reconsider:
- College choice
- Institutional aid opportunities
- Merit scholarship strategy
- Family contribution
- Work options
- Borrowing
- Appeal options
That is strategic financial planning.
Common Mistakes That Make Financial Aid Harder
Mistake 1: Looking Only at Tuition
Housing and other living expenses can significantly affect the actual cost of attendance.
Mistake 2: Treating Every Dollar of Aid as Equal
A grant, work-study award, and loan have different financial consequences.
Mistake 3: Choosing a College Based on Sticker Price
The published price does not tell the entire story.
Mistake 4: Searching for Scholarships Too Broadly
A targeted search is generally more useful than applying randomly.
Mistake 5: Ignoring International-Aid Policies
International applicants should verify each institution’s policy rather than assuming domestic aid rules apply to them.
Mistake 6: Missing Secondary Deadlines
A college may have separate admission, scholarship, and financial-aid deadlines.
Mistake 7: Ignoring Renewal Conditions
A scholarship should be evaluated across the years you expect to rely on it.
Mistake 8: Assuming FAFSA Is the Entire Process
Some colleges and programs require additional forms.
Mistake 9: Waiting Until Admission to Think About Affordability
Financial fit should influence the college list before applications are submitted.
Mistake 10: Focusing on the Largest Scholarship Instead of the Largest Funding Gap
A $10,000 award is valuable, but its importance depends on the size of the remaining gap.
The Financial-Aid Decision Framework
If you remember only one framework from this article, use this:
Step 1: Know Your Cost
Calculate the realistic annual cost.
Step 2: Know Your Eligibility
Determine which aid programs you can actually use.
Step 3: Find Institutional Aid
Research what each college offers to students like you.
Step 4: Complete Required Forms
FAFSA, CSS Profile, institutional applications, and scholarship forms as applicable.
Step 5: Search Strategically
Target scholarships based on your actual profile.
Step 6: Calculate the Funding Gap
Do not stop at the award amount.
Step 7: Compare Colleges
Look at net cost, not sticker price.
Step 8: Check Four-Year Sustainability
Investigate renewal rules and future costs.
Step 9: Appeal When Circumstances Justify It
Provide clear evidence when your financial situation has materially changed.
Step 10: Choose the Sustainable Option
The best financial decision is not necessarily the college offering the largest aid package.
It is the option that provides a strong academic and personal fit without creating an unreasonable financial burden.
Common Questions About Financial Aid for College in the U.S.
1. Can I get financial aid if my family earns too much?
Do not assume that income alone answers the question. Different programs and institutions use different eligibility criteria. If you are eligible to submit FAFSA, completing it can also provide information used by states, colleges, and other aid providers.
2. Is FAFSA the same as a financial-aid offer?
No. FAFSA is an application used to determine eligibility and provide information to aid programs. The college ultimately determines the aid it offers. Federal Student Aid specifically distinguishes estimated eligibility information from the final school financial-aid offer.
3. Do international students qualify for financial aid in the U.S.?
Some do, depending on the institution and program. International students should focus heavily on college-specific institutional aid and scholarships rather than assuming federal student aid is available. EducationUSA provides a searchable financial-aid resource for international students.
4. Does every college require the CSS Profile?
No. CSS Profile is used by participating colleges and scholarship programs for non-federal institutional aid. Check the requirements of each college individually.
5. Is work-study free money?
No. Work-study is earned through eligible employment. It can help students pay education expenses, but it should not be treated as equivalent to a grant or scholarship.
6. What if my financial situation changes after I submit FAFSA?
Contact your college’s financial-aid office and explain the change. Ask whether the school has a process for reviewing changed financial circumstances or reconsidering your aid. Provide documentation if requested.
7. Should I apply for hundreds of scholarships?
Not necessarily. A targeted group of scholarships that match your eligibility, background, interests, and qualifications may be a better use of time than submitting low-quality applications to hundreds of unrelated opportunities.
Read More: 10 Essential College Freshman Tips for a Successful First Semester
Your Final Financial-Aid Checklist
Before making a college decision, you should be able to answer all of these questions:
About the College
- What is the total estimated cost of attendance?
- What is my estimated net price?
- How much institutional aid might I receive?
- Is the aid renewable?
About Applications
- Do I need FAFSA?
- Do I need CSS Profile?
- Does the college require an additional financial-aid form?
- Are there separate scholarship deadlines?
About Scholarships
- Which scholarships fit my profile?
- Which local scholarships are available?
- Which major-specific scholarships are available?
- Which awards are renewable?
About the Aid Offer
- How much is grant money?
- How much is scholarship money?
- How much is work-study?
- How much is borrowing?
- What amount must my family actually pay?
About Long-Term Affordability
- What is my first-year funding gap?
- What could my four-year funding gap be?
- What happens if a scholarship is not renewed?
- How much would I need to borrow?
- Is the college still affordable if my expected funding does not materialize?